


Cape San Blas Homeowners Insurance: Understanding CBRA Zones, FEMA Flood Insurance, and Vacation Rental Coverage
Buying or owning a home on Cape San Blas, Florida, comes with unique insurance considerations that every property owner should understand.
Located along Florida's Forgotten Coast in Gulf County, Cape San Blas is known for beautiful beaches, luxury vacation rentals, and coastal investment properties. However, its location between the Gulf and St. Joseph Bay means homeowners must carefully evaluate hurricane coverage, flood risks, insurance eligibility, and rental property protection.
Have questions? Contact Kam Ashabranner for more information: Click here to book a time
What Is a CBRA Zone on Cape San Blas?
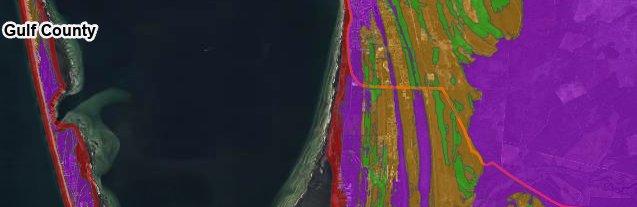
One of the most important things to understand before purchasing property on Cape San Blas is the Coastal Barrier Resources Act, commonly called CBRA.
CBRA is a federal law that limits certain federally funded activities in designated coastal areas. These areas are part of the Coastal Barrier Resources System (CBRS).
Cape San Blas contains designated CBRS areas, including federal mapping units P30 and P30P.
Why does this matter for insurance?
Properties located within a CBRS designation are generally ineligible for new federal flood insurance through FEMA's National Flood Insurance Program (NFIP), although exceptions exist for certain qualifying older structures.
Private flood insurance may still be available, depending on the property and insurance carrier.
Not every home on Cape San Blas is located within a CBRS designation. Buyers should confirm their exact property location using the U.S. Fish and Wildlife Service CBRS Mapper.
A CBRA designation is different from a FEMA flood zone. A property can be located in both a high-risk FEMA flood zone and a CBRS area.
Understanding FEMA Flood Zones on Cape San Blas
FEMA identifies flood hazards through its Flood Insurance Rate Maps.
Common flood zone classifications include:
-
Zone AE: High-risk flood area with a designated base flood elevation.
-
Zone VE: Coastal high-risk area exposed to additional wave hazards.
-
Zone X: Lower or moderate mapped flood risk, although flooding is still possible.
Properties in Zones AE or VE commonly require flood insurance when financed with a federally backed mortgage, subject to applicable eligibility rules.
Importantly, most standard homeowners insurance policies do not cover flooding or storm surge.
Flood insurance generally must be purchased separately through the NFIP, when eligible, or through a private flood insurance carrier.
Homeowners Insurance vs. DP3 Insurance: What's the Difference?
The way you use your Cape San Blas property can significantly affect which insurance policy is appropriate.
HO3 Homeowners Insurance
An HO3 policy is typically designed for an owner-occupied primary residence or an eligible secondary home.
Depending on policy terms, coverage may include:
-
Dwelling and structural damage
-
Personal belongings
-
Personal liability
-
Additional living expenses
-
Wind and hurricane damage when included
However, standard homeowners policies may exclude or restrict coverage for regular short-term rental operations.
DP3 Dwelling Insurance
A DP3 policy is commonly used for rental properties and certain non-owner-occupied homes.
DP3 coverage may include:
-
Dwelling protection
-
Certain attached and detached structures
-
Loss of rental income following covered damage, when included
-
Optional personal property coverage
-
Optional or separately purchased liability coverage
A DP3 policy is not automatically a complete vacation rental insurance policy.
Owners operating Airbnb or Vrbo properties must confirm that short-term rental activity is specifically permitted by their insurance carrier.
Some properties may need specialized vacation rental or commercial insurance coverage.
How Much Does Homeowners Insurance Cost on Cape San Blas?
Cape San Blas insurance premiums vary considerably based on the property.
A home's replacement cost, construction type, roof age, wind mitigation features, elevation, flood exposure, and occupancy all influence insurance pricing.
A luxury Gulf-front vacation rental may have substantially different insurance requirements than an inland primary residence.
For an accurate estimate, owners should obtain an address-specific quote rather than rely on a general coastal insurance average.
Flood insurance is typically a separate expense and must be considered when calculating total annual ownership costs.
Hurricane Deductibles and Wind Mitigation
Florida coastal homeowners should also understand hurricane deductibles.
Unlike a traditional flat deductible, hurricane deductibles are commonly calculated as a percentage of the insured dwelling value.
For example, a property insured for $750,000 with a 2% hurricane deductible would have a $15,000 deductible for a covered loss subject to that deductible.
Wind mitigation improvements, including roof-to-wall connections, hurricane-rated openings, and qualifying roof construction, may help reduce insurance premiums.
Owners should also review ordinance or law coverage, replacement cost provisions, pool liability, and loss of rental income protection.
Why Independent Insurance Agencies Matter on Cape San Blas
Coastal properties are not always straightforward to insure.
Some insurance companies restrict coastal exposure, short-term rentals, older roofs, or certain flood-prone locations.
An independent insurance agency can compare available carriers and help property owners understand the differences between policies.
One local company, Insuring the Coast, works with homeowners, vacation rental investors, real estate professionals, and coastal property owners throughout Cape San Blas, Port St. Joe, Mexico Beach, and surrounding communities.
Whether you're purchasing your first beach house or managing multiple investment properties, understanding your insurance options before closing can help prevent costly surprises.
Reach out to your agent to get more information or contact a local company today. Your real estate professional can also help obtain quotes for you.
Get a Cape San Blas Insurance Quote Today (local company to PSJ)
Insuring the Coast | Independent Insurance Agency
Phone: 850-203-3643
Email: Quotes@InsuringTheCoastFL.com
Website: https://www.insuringthecoastfl.com
Selling the Coast Fl
402 Reid Avenue
Port St Joe, Fl
32456